Table of Contents
- What Portfolio Balance Really Means
- Start With Goals, Time Horizon, And Risk Tolerance
- Build Diversification Across Major Asset Classes
- Spread Risk Within Each Asset Class
- Check For Hidden Overlap In Funds And ETFs
- Use Geographic Exposure With Care
- Why Diversification Does Not Remove All Risk
- Create A Simple Portfolio Review Process
- Common Portfolio Balance Mistakes
- Questions Readers May Have
- Practical Checklist
- Keep The Portfolio Clear And Purposeful
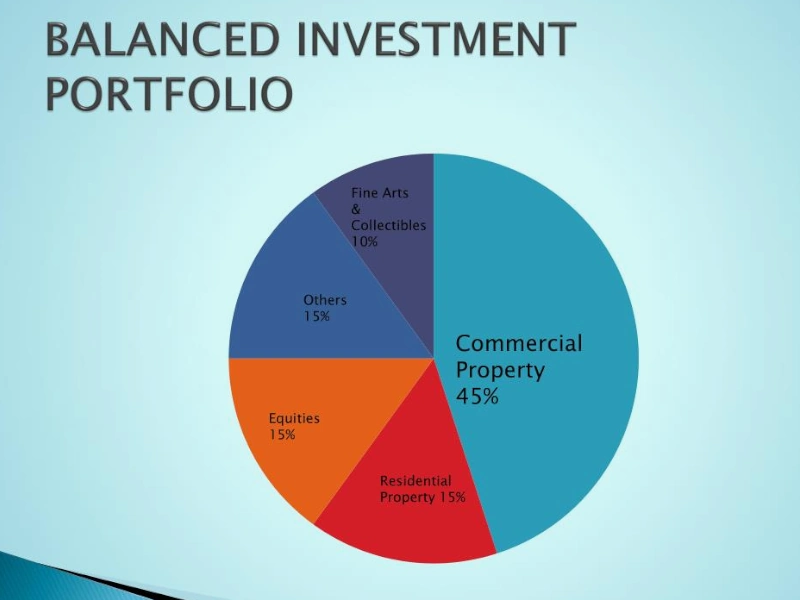
A balanced portfolio is more than a long list of investments. Owning several stocks or funds can still leave you exposed to the same companies, sectors, countries, or market trends. The goal is not to own everything. It is to hold investments that serve clear roles and fit the time you have, the goals you are pursuing, and the level of uncertainty you can realistically accept.
For Canadian investors, Questrade, a Canadian online investing platform, explains why diversification matters through education on asset allocation, ETFs, geographic exposure, and rebalancing. Its guidance is useful because it focuses on practical ways investors can diversify their exposure rather than relying on a single stock, industry, or market. Diversification cannot guarantee a profit or prevent losses, but it can reduce the impact of a problem in one part of a portfolio.
What Portfolio Balance Really Means
Portfolio balance combines four related ideas:
- Asset allocation: How money is divided among stocks, bonds, cash, and other categories.
- Diversification: Spreading investments across different holdings within and across those categories.
- Concentration risk: The risk that too much depends on one company, sector, asset type, or region.
- Rebalancing: Bringing the portfolio back toward its intended mix after market movements change it.
For example, a portfolio built mostly around one technology stock may rise quickly when that company does well, but it also depends heavily on a single business and sector. A portfolio with stocks, bonds, cash for near-term needs, and exposure across industries has more sources of return and risk. Neither approach is automatically right for everyone, but the second is generally less dependent on one outcome.
Start With Goals, Time Horizon, And Risk Tolerance
Before choosing investments, define what the money is for. Retirement savings, a home down payment, education costs, and long-term wealth building may call for different approaches. Next, estimate when you expect to need the money. A goal that is several decades away may allow more time to recover from market declines than a goal due within a few years.
Your ability to take risk is not the same as your comfort with risk. Someone may feel comfortable with market swings but still need a conservative approach because the money is needed soon. Another person may have a long time horizon but find sharp declines emotionally difficult. The relationship between asset allocation, time horizon, and risk tolerance is personal, so copying another investor’s mix is rarely a complete plan.

Build Diversification Across Major Asset Classes
Different asset classes can respond differently to economic conditions, though they can also decline simultaneously. A portfolio might include:
- Stocks for long-term growth potential, with potentially larger price swings.
- Bonds for potential income and a different type of market exposure.
- Cash and cash equivalents for liquidity and short-term spending needs.
- Real assets such as real estate, infrastructure, or commodities, where appropriate.
- International investments to avoid relying entirely on one national economy.
Adding more holdings only helps when those holdings add meaningfully different exposure. Five investments affected by the same interest-rate shift or technology cycle may offer less balance than their number would suggest.
Spread Risk Within Each Asset Class
Stock diversification can involve company size, industry, geography, and investment style. Holding several technology companies is still a bet on the sector. Bond diversification can involve different issuers, credit qualities, maturities, and regions. Investors should also consider employer stock carefully, because a job and an investment account can both be affected if the same company struggles.
Correlation is a useful concept here. In plain language, it describes how closely investments tend to move together. Investments that often react similarly may not provide much protection from each other during a downturn.
Check For Hidden Overlap In Funds And ETFs
Funds and ETFs can provide broad exposure, but they are not automatically diversified. A narrow sector fund, a themed ETF, or several funds with the same major holdings can create overlap. A simple review process can uncover it:
- List every fund, ETF, stock, bond, and other holding.
- Review each fund’s largest positions.
- Group exposure by company, sector, country, and asset class.
- Look for repeated ownership of the same large companies.
- Compare fees, investment styles, and the indexes funds track.
Simply owning many funds does not eliminate concentration risk. As guidance on concentration risk notes, overlap can occur when individual stocks, sector funds, and broad index funds all hold similar securities.
Use Geographic Exposure With Care
Investing in only one country can make a portfolio especially dependent on local economic conditions, regulations, and currency movements. Exposure to U.S., European, Asian, and emerging markets may broaden the opportunity set, but international investing also introduces currency and political risks. Global markets can still decline together during broad periods of market stress, so geographic diversification is only one layer of a wider plan.
Why Diversification Does Not Remove All Risk
Diversification is most helpful against company-specific risk, such as a disappointing earnings report or a business failure. It cannot remove market-wide risks, including recessions, inflation shocks, interest-rate changes, or widespread investor fear. During a major market event, stocks in different industries can fall together because the pressure affects the overall market. A risk-free portfolio does not exist.
Create A Simple Portfolio Review Process
A review once or twice a year is often more useful than reacting to every headline. Compare your current allocation with your intended target, identify positions that have become too large, and revisit whether your goal or time horizon has changed. New contributions can sometimes be directed to underweighted areas before selling investments. Before making changes, consider taxes, fees, trading costs, and whether you may need the money soon.
Common Portfolio Balance Mistakes
- Letting employer stock become a large share of savings.
- Buying several funds without checking their top holdings.
- Assuming a popular sector will always lead the market.
- Leaving an old allocation unchanged after a major life event.
- Buying based mainly on recent performance.
- Trading frequently in response to news coverage.
- Ignoring fees, taxes, liquidity, and account type.
Questions Readers May Have
How Many Investments Are Needed To Be Diversified?
There is no universal number. What matters is how different the holdings are and whether they overlap.
Can One ETF Provide Enough Diversification?
A broad-market ETF may offer wide exposure, while a sector or theme ETF may be highly concentrated. Review what the fund actually owns.
Is A 60/40 Portfolio Suitable For Everyone?
No standard allocation is a personal recommendation. Goals, income needs, time horizon, and risk tolerance should guide the mix.
How Often Should A Portfolio Be Rebalanced?
Some investors use annual reviews, while others use preset allocation thresholds. Either approach should follow a written plan rather than a market prediction.
Practical Checklist
- Write down every investment and its purpose.
- Measure exposure by asset class, sector, country, and company.
- Check fund holdings for overlap.
- Match the portfolio to current goals and timeline.
- Set a rebalancing rule before markets become stressful.
- Seek qualified advice for complex tax, retirement, or estate planning decisions.
Keep The Portfolio Clear And Purposeful
A balanced portfolio is not about owning every available investment. It is about deliberately spreading exposure, finding hidden concentrations, and keeping decisions connected to real financial goals. Review the plan periodically, make changes thoughtfully, and allow the portfolio to evolve as your life and needs change.